Audiovisual production insurance: coverage and importance
Why is audiovisual production insurance essential?
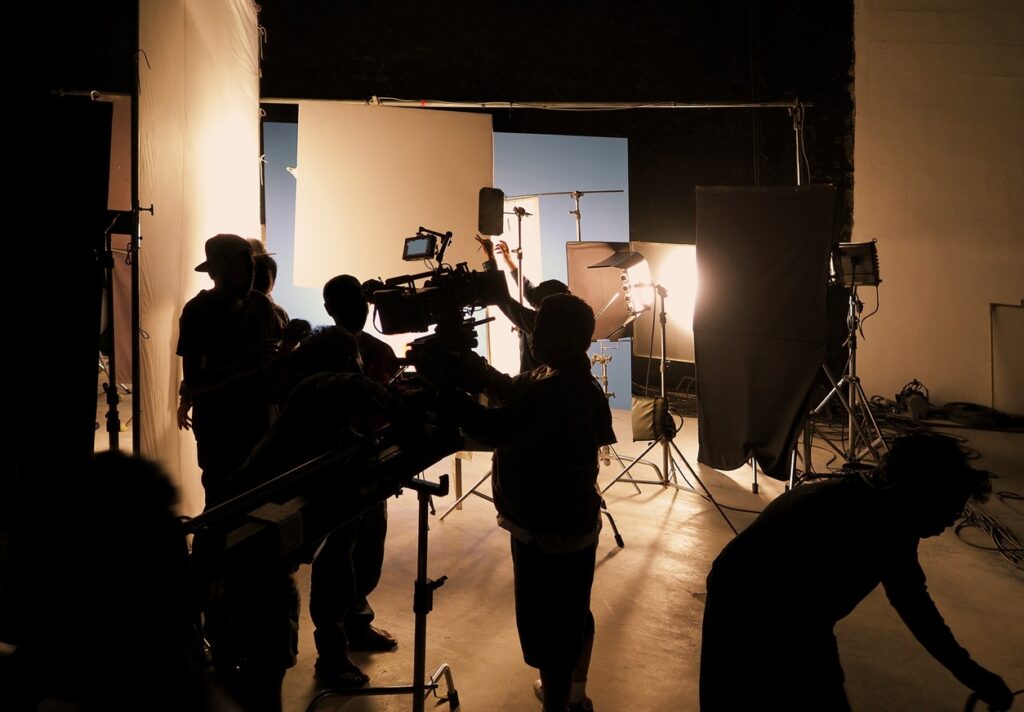
Audiovisual production insurance. In every professional shooting, multiple risks coexist: high-value equipment, changing locations, and a large number of exposed personnel. Even the smallest mistake can lead to significant losses. An operator could accidentally damage a camera, drone, or lighting equipment. Without adequate insurance, the costs of repair or replacement would fall directly on the producer or professional.”
In addition, both the technical team and actors can suffer accidents (falls, electrocutions, etc.) that may lead to claims.
A specific insurance not only protects financially in these scenarios, but also ensures the continuity of the project.
On the other hand, compliance with regulations is key. To operate in public spaces, municipalities and agencies require insurance.
Civil Liability (RC) that covers damages to third parties
In fact, the filming permit usually requires formally including a “civil liability insurance” in the documentation.
Collective agreements in the audiovisual sector also establish mandatory minimum coverage (for example, in cases of work-related accidents involving contracted staff).
Similarly, platforms (Netflix, RTVE, etc.) and support funds require a valid policy certificate.
In short, audiovisual insurance is a legal and strategic requirement to protect investments and avoid costly penalties or claims.
Key coverages
Audiovisual production policies are modular, but these basic guarantees are usually included:
General Civil Liability (CR).
It covers personal injuries or damagerial caused to third parties during filming
For example, if a camera falls and damages a pedestrian's car, the policy covers the repair costs.
It also covers claims for injuries to the public or external workers, and even damage to non-affiliated decorations.
Audiovisual Equipment Insurance.
Protects therial technical equipment –cameras, spotlights, drones, etc.– from accidental damage, theft, or loss during filming and transportation
For example, if a drone crashes or a spotlight gets wet in the rain, the coverage pays for the repair or replacement.
Some policies even cover rented equipment.
Equipment accidents (Employer's Liability).
It includes the coverage of occupational accidents for technical and artistic personnel (actors, cameramen, sound technicians, extras). It is known as employer liability: “employee claims for injuries or illnesses suffered during production”
This allows for medical expenses or compensation for injuries sustained on set, such as falls, blows or illnesses.
Cancellation or interruption of filming.
Sometimes included in comprehensive policies or as an extra. It covers additional costs if production has to be halted due to unforeseen circumstances (illness of a key actor, weather conditions, location problems that cannot be rectified). For example, it can cover compensation to suppliers or the cost of reshoots if a shoot is postponed.
Damage to locations and sets.
It covers material damage to the places where the film is shot (houses, buildings, monuments) or to sets built for the film. A mistake in the electrical installation that causes a fire on the set, for example, would be covered.
Loss of recorded material.
Some advanced policies include the cost of repeating shots if the original filmrial is lost (due to technical failure, accidental deletion, theft of hard drives, etc.).
This ensures that the investment in filming is not completely lost.
Factors influencing price
The premium for audiovisual insurance depends on many variables:
Shooting budget.
Larger production means higher premiums.
Coverage contracted and sums insured.
More guarantees (e.g. including cancellation or very expensive equipment) increase the price.
Duration of filming.
Insuring 1 week is much cheaper than 6 continuous months.
Value of technical equipment.
The higher the declared value of cameras, drones and equipment, the higher the premium.
Locations.
Filming on location or in several countries (logistical risk) tends to make the policy more expensive.
Producer history.
Customer experience and claims experience are also considered.
Checklist for audiovisual insurance
Analyse the risks of the project: where is it shot, what scenes have pyrotechnics or action, will there be drones? Each element adds risks to be adjusted in the policy.
Verify coverage and limits:
Ensure that the capital sums cover the actual value of equipment and possible indemnities (e.g. CR of at least €1M to cover major damage).
Include all key assets and persons:
Declare all equipment, locations, and cast involved (for employer's liability). Do not omit guest actors or hired equipment.
Plan ahead:
Ideally, insurance should be taken out at the pre-production stage. Taking it out “last minute” can limit options and create gaps in coverage.
Consult a specialised broker:
An experienced A/V broker (such as PIB Group Iberia) can advise on the best combination of hedges and negotiate preferential terms.
Why choose PIB Group Iberia?
At PIB Group Iberia, we are specialists in corporate and specialty insurance, with extensive experience advising the audiovisual sector.
Our approach is consultative: we analyze each production, identify specific risks, and negotiate the most comprehensive coverage with various insurers, always focused on providing total protection for our clients. Trust our multidisciplinary team to ensure that your production has the appropriate protection, and we process the policy quickly and personally.
Speak to a specialist advisor and ask for here more information without obligation.